
House hacking is a powerful wealth-building strategy that allows you to live in a property while renting out portions of it to offset or completely cover your housing expenses. By generating rental income from extra bedrooms, separate units, or other spaces, you can dramatically reduce your cost of living while building equity. As part of our comprehensive rental property calculators collection, this calculator helps you analyze the financial impact of house hacking and determine how much you can save or earn by implementing this strategy.
Calculate House Hacking Profitability
Please input the required fields (*) below to calculate your net housing costs from house hacking.
House Hacking Calculator
This calculator is meant for educational purposes only. The calculation generated from this calculator does not, and is not intended to, constitute financial advice. As such, all information, content, and materials available on this site are for general informational purposes only. Please review our Editorial Standards for more info.
House Hacking Calculation Formula
Our house hacking calculator formula examines the net housing cost if you use your rental property for house hacking. The formula is below:
Net Housing Cost = (Mortgage Payment1 + Property Taxes2 + Insurance3 + Other Expenses4) – Tenant Income5
1. Mortgage Payment – This is the total monthly mortgage payment.
2. Property Taxes – This is the total monthly property tax payments.
3. Insurance – This is the total monthly insurance payments.
4. Other Expenses – This is any other monthly expenses such as HOA, utilities, maintenance, etc.
5. Tenant Income – This is the total monthly amount of rent received from the tenant or multiple tenants.
This calculation calculates the overall net housing cost if you are to house hack. A positive numbers (+) is the amount you would have to pay per month for housing costs. A negative number (-) is the profit you would receive every month from house hacking.
House Hacking Calculation Example
Suppose you purchase a duplex with an owner-occupied loan, planning to live in one unit and rent out the other. Your monthly costs are a $2,200 mortgage payment, $350 in property taxes, $150 in insurance, and $200 in other expenses for utilities and maintenance. The second unit rents for $1,800 per month. The house hacking calculation would be:
($2,200 + $350 + $150 + $200) − $1,800 Tenant Income
= $1,100 Net Housing Cost
The positive result means you pay $1,100 per month to live in your own property. If comparable apartments in your area rent for $1,800, house hacking saves you $700 every month, or $8,400 per year, while a tenant helps pay down your mortgage and you build equity.
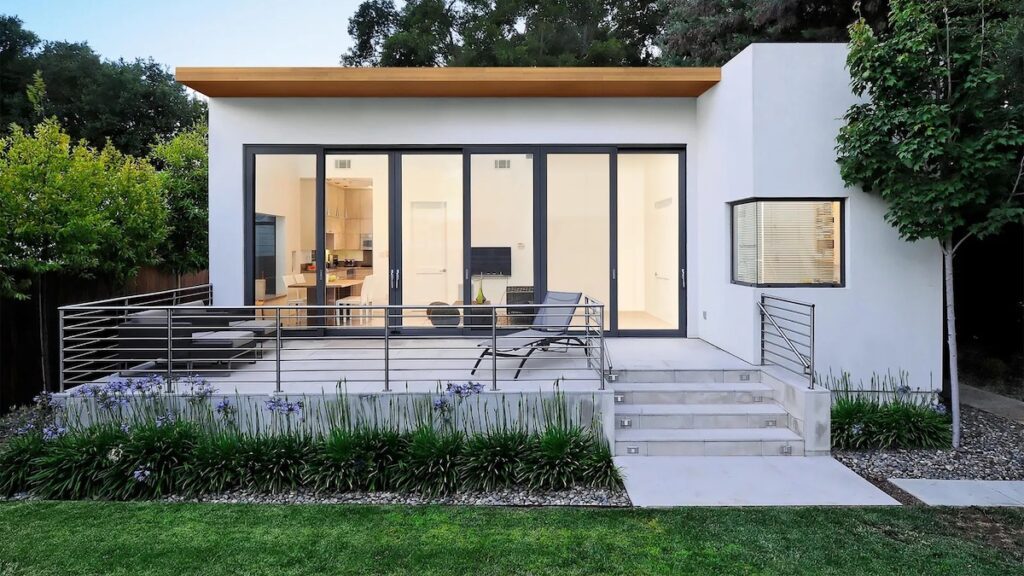
Now suppose you also rent a spare bedroom in your unit for $700 per month, bringing tenant income to $2,500. Net housing cost drops to $400. Push tenant income above your $2,900 in total expenses, for example by adding an ADU, and the number turns negative, meaning you get paid to live there. Use the house hacking calculator above to test different rent scenarios and see how close your property can get to covering your housing costs completely.


House Hacking Resources
What is House Hacking?

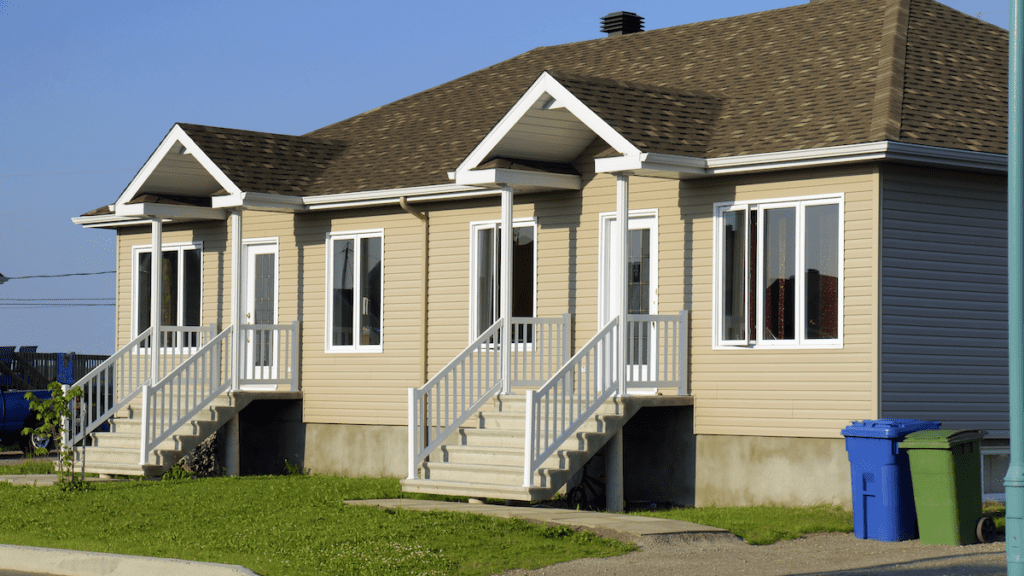
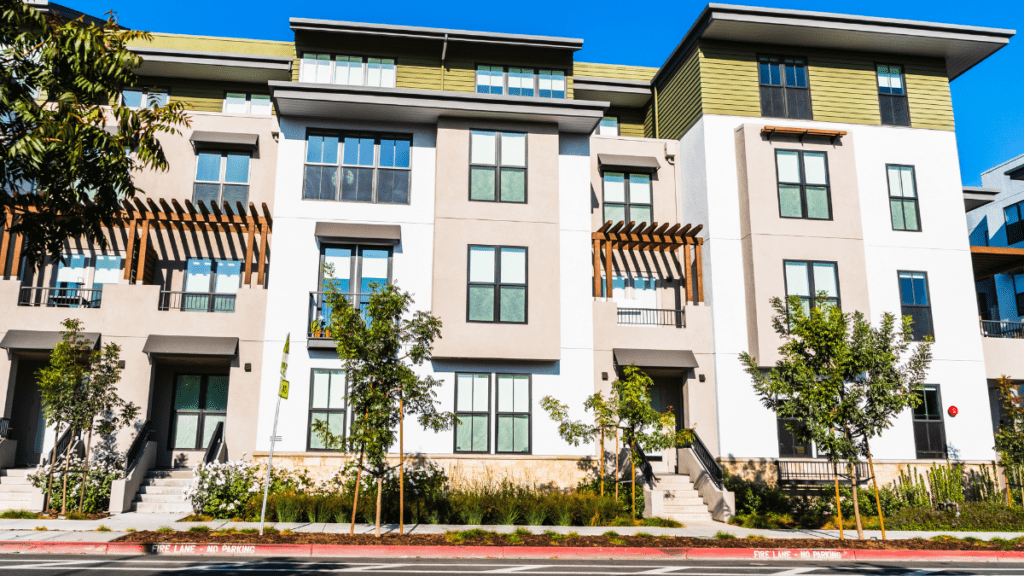
House Hacking is a rental real estate investing strategy that involves renting part of a property out to generate additional rental income and/or reduce living expenses at the same time.
Search Rental Real Estate
Try searching our site for hundreds of rental property topics including loans, investor tool reviews, real estate companies, property management tips and more.
House Hacking Calculator FAQ
What are the Pros and Cons of House Hacking?
House hacking offers significant financial advantages for those willing to share their living space or property with tenants, but it also comes with unique challenges that differ from traditional homeownership. Understanding both the benefits and drawbacks helps you determine whether this strategy aligns with your financial goals and lifestyle preferences.
| Pros | Cons |
|---|---|
| Significantly reduces or eliminates monthly housing costs | Loss of privacy and potential lifestyle adjustments from sharing property |
| Builds equity while tenants help pay your mortgage | Landlord responsibilities including maintenance, repairs, and tenant management |
| Qualifies for owner-occupied financing with lower down payments | Must comply with landlord-tenant laws and fair housing regulations |
| Provides hands-on real estate investing experience with reduced risk | Potential conflicts or difficult situations with tenants living nearby |
| Tax benefits including deductions for rental portion expenses | Limited flexibility to move without converting to full investment property |
| Creates passive income stream while living on the property | May face challenges qualifying for future mortgages due to debt-to-income ratios |
| Opportunity to learn property management skills | Noise, scheduling conflicts, and shared common areas can cause stress |
How Much Can I Realistically Save Through House Hacking?
Savings vary widely based on your market, property type, and rental income potential, but many house hackers reduce their housing costs by 50-100%. Some investors even achieve “living for free” when rental income covers their entire mortgage payment, property taxes, insurance, and utilities, allowing them to save or invest what would otherwise go toward housing expenses.
What Types of Financing Options are Available for a House Hacking Property?
House hacking properties often qualify for owner-occupied financing, which typically offers lower down payments (as low as 3-5% with conventional loans or 3.5% with FHA loans) and better interest rates compared to investment property loans. VA loans for eligible veterans can even offer zero down payment options, making house hacking accessible to first-time investors with limited capital.


