
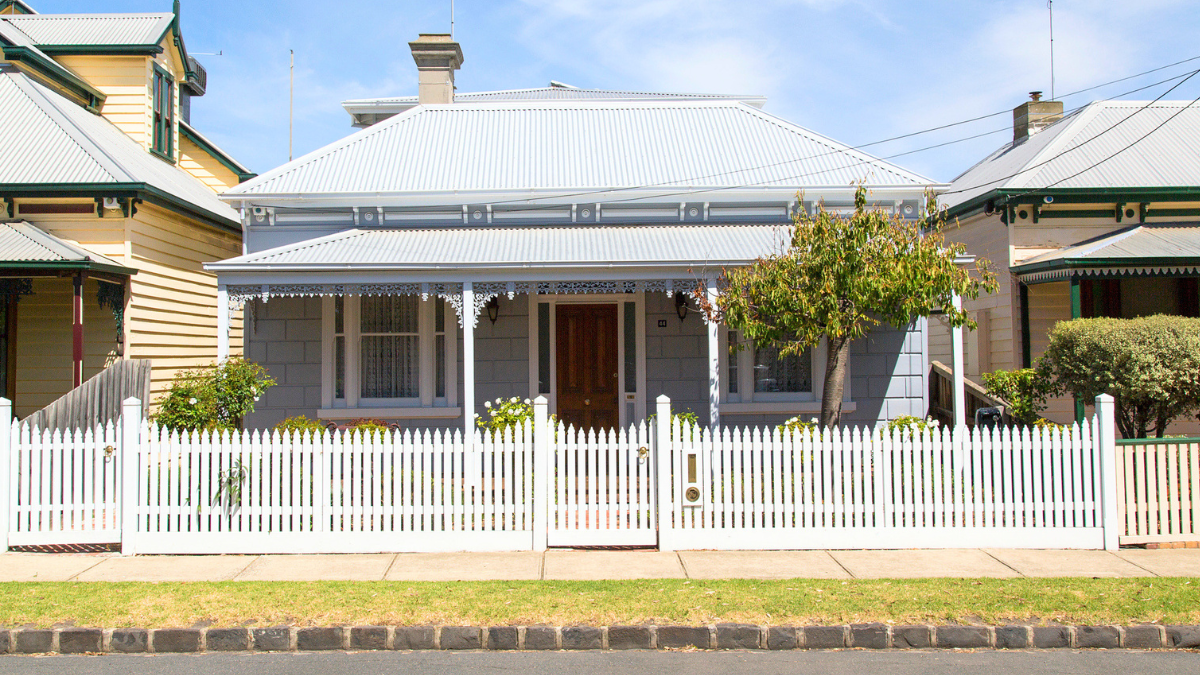
A period home with high ceilings and original details photographs well and rents fast. What it doesn’t advertise is the maintenance file waiting behind the walls, or the tax position that’s quietly less favourable than a newer alternative.
Landlords who buy on charm alone often find the real cost of that character shows up later, in a depreciation schedule that delivers less than expected, or a repair bill that arrives without warning.
The Tax Position is Weaker Than Most Landlords Assume
Depreciation is one of the more valuable tax levers a property investor has, and age determines how much of it is actually available. Properties built before 16 September 1987 are not eligible for capital works deductions at all, unless they’ve undergone substantial renovation since mid-1985, in which case only the renovated component may qualify.
Only properties built after that date can be depreciated each year until the building turns 40. A landlord holding a genuinely old property, one built well before the cut-off and never substantially renovated, is simply locked out of a deduction a newer property claims automatically.
Plant and equipment adds another layer. Since May 2017, second-hand fittings already in a property when it’s purchased, carpets, blinds, ovens and the like, can no longer be depreciated at all. Only new items bought directly by the landlord qualify. An older rental, furnished with older fittings, offers noticeably less to claim than a freshly built one where everything starts its depreciation clock from day one.
The Maintenance Bill Rarely Stays Where You Budgeted it
Property managers consistently describe the same pattern: rental ownership looks passive on paper and rarely is, and the gap between the two shows up most in older housing stock. Ageing systems mean taps, heaters and hot water units fail at inconvenient moments, and emergency callouts always cost more than a scheduled one.
Compliance adds a second, less visible layer, annual smoke alarm checks, electrical and gas safety inspections, and in some states pool fencing or minimum housing standard upgrades, all of which apply regardless of a property’s age but tend to surface more often, and more expensively, in a home whose systems were never built to current standards.
Landlord insurance compounds this. Many owners assume standard cover extends to a rental, then discover only a dedicated landlord policy protects against loss of rent, malicious tenant damage or liability claims, and that cheaper policies often carry higher excesses that make a claim barely worth lodging. None of this is unique to older homes, but ageing wiring, roofing and plumbing all raise the odds that a claim gets made in the first place.
Vacancy is the Quiet Budget Killer, and Older Stock Feels it More
Every week a property sits empty between tenancies, the mortgage, rates and utilities keep accruing with nothing coming in to offset them. Presentation matters here more than most landlords expect: a property that needs patching, repainting or updating before it’s move-in ready simply takes longer to re-let than one that doesn’t, and an older home more often needs that work between leases.
Even “Affordable” Entry Points Aren’t What They Used to be
It’s worth noting that the price gap between old and new isn’t always as wide as landlords assume. Recent reporting on Sydney’s property market has flagged that even entry-level, unrenovated homes in some inner-city suburbs are now crossing the $2 million mark, properties with no particular luxury finish, simply priced there because of the land beneath them.
When an older, unremarkable home commands that kind of price without the depreciation benefits or the tenant appeal of something new, the comparison against a fresh-build alternative in a growth corridor becomes a lot more direct.
Where New-Build Shifts the Calculation
A newly constructed rental starts from a cleaner position on every count above. Wiring and plumbing meet current code by default. Every fitting is new and depreciable from the day the tenant moves in. Builder warranties typically cover structural elements and major systems for the first several years, shifting a meaningful share of early repair risk away from the landlord entirely.
That gap tends to be widest in growth corridors, where new supply is being delivered alongside the infrastructure and amenity that keeps a rental in demand. For landlords weighing up where to buy new-build stock, house and land packages in Central Coast are worth a look precisely because they pair fresh construction with the population growth that keeps a property tenanted.
The Practical Takeaway
Before buying on charm, run the full numbers a period property will actually cost across a five or ten year hold, the depreciation you’ll miss out on, the maintenance reserve, the insurance premium, the vacancy assumption. Weigh that against a new-build alternative with a warranty still in effect and a full depreciation schedule ahead of it. The character property might still win on price or rental yield. But it should win on the complete ledger, not just the listing photos.
About the Author
Ryan Nelson
I’m an investor, real estate developer, and property manager with hands-on experience in all types of real estate from single family homes up to hundreds of thousands of square feet of commercial real estate. RentalRealEstate is my mission to create the ultimate real estate investor platform for expert resources, reviews and tools. Learn more about my story.