
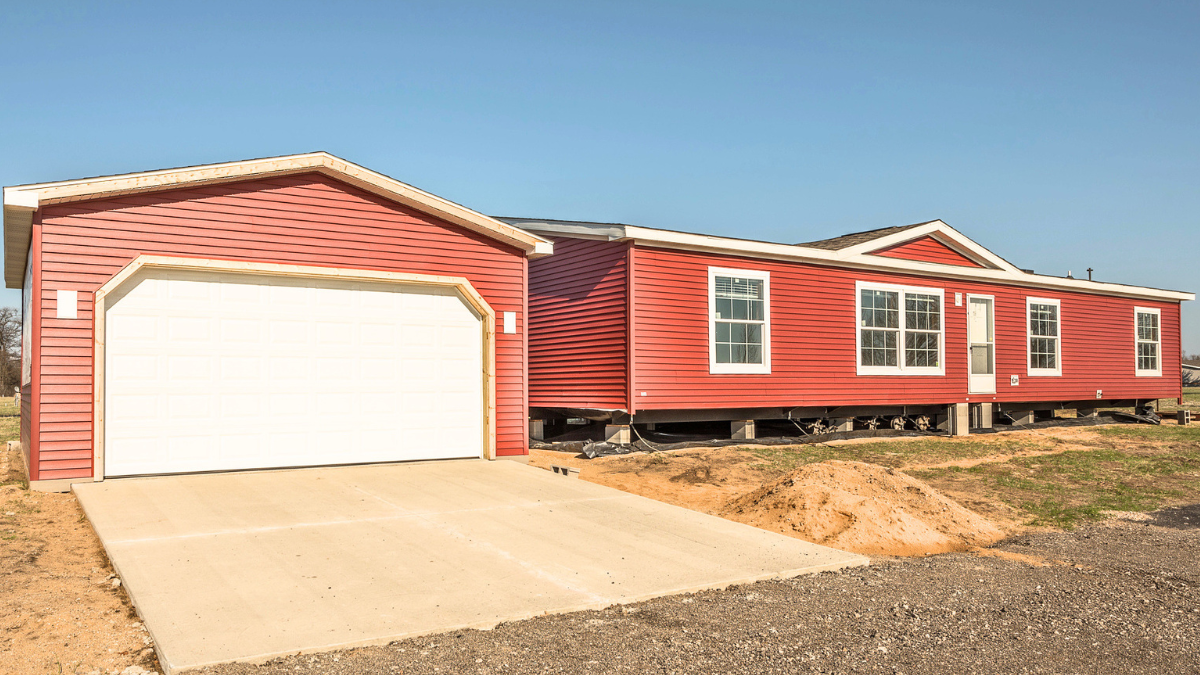
Do Manufactured Homes Depreciate? If you were to ask a real estate agent and a tax accountant this question, you’d likely get two very different answers. That’s because “depreciate” carries different meanings in their respective fields.
For one, it’s all about market value, while for the other, it pertains to your tax deductions. Investors who mix up the two either overpay for a manufactured home community or leave deductions on the table.
Here’s how each type of depreciation actually works, and why the distinction matters more than ever after OBBBA (One Big Beautiful Bill Act).
Market Value: Manufactured Homes Don’t Have to Lose Value
The old assumption is that manufactured homes depreciate like cars. Buy one, and it loses value the moment it leaves the factory.
That assumption holds less often than people think. A manufactured home titled as personal property, sitting on rented land, does tend to lose market value over time, similar to a vehicle. But a manufactured home permanently affixed to a foundation on land the owner controls behaves like any other structure. Its value tracks location, condition, and local demand, the same factors that drive prices for site-built homes.
For investors, the practical takeaway is this: land ownership and permanent attachment change the asset class. A single manufactured home on a rented lot is a different investment than a manufactured housing community where you own the land, the infrastructure, and, in many cases, the homes themselves.
Tax Depreciation: Manufactured Homes Absolutely Depreciate, and the Rules Are Specific
This is where cost segregation comes in, and where the real dollars are. The IRS depreciates manufactured homes based on how they’re classified, not on what they’re called in casual conversation. Three classifications show up most often:
Real property (27.5-year residential or 39-year commercial). A manufactured home permanently affixed to a foundation, connected to utilities, and rented out as a dwelling gets treated like any other residential rental building. It depreciates on the standard 27.5-year schedule.
Personal property (5-year). Under Section 168, a manufactured home that isn’t permanently affixed, and still carries its axle and VIN, can qualify as 5-year property. This applies most often to homes owned and leased out within a manufactured housing community, where the home itself remains a separate, movable asset from the land underneath it.
Land improvements (15-year). The infrastructure inside a manufactured housing community, roads, utility hookups, pads, and site improvements, depreciates separately from both the homes and the land. These typically fall into the 15-year recovery class.
That three-way split is exactly the kind of asset mix a cost segregation study is built to untangle.
Why OBBBA Changed the Math for Manufactured Housing Communities
Before OBBBA, bonus depreciation was phasing down toward zero. A 5-year or 15-year asset still recovered faster than a 27.5-year building, but the accelerated first-year deduction was shrinking every year.
OBBBA permanently restored 100% bonus depreciation for qualified property with a recovery period of 20 years or less. That covers both the 5-year home classification and the 15-year land improvement classification.
In practice, this means an investor acquiring a manufactured housing community can often expense the majority of the purchase price, excluding land, in the first year. Homes that qualify as 5-year personal property and infrastructure that qualifies as 15-year land improvements both get the full 100% write-off. Only the underlying land and any components with a recovery period longer than 20 years fall outside that treatment.
For a community where 80% of the purchase price sits in movable homes and site infrastructure, that’s a substantial first-year deduction that didn’t exist at this scale before OBBBA.
Where This Gets Misclassified
Manufactured housing depreciation is one of the more commonly miscategorized areas in real estate tax. A few situations to watch for:
- State law varies on what counts as real vs. personal property. Some states title manufactured homes as personal property regardless of how they’re affixed, which affects both the depreciation schedule and how a cost segregation study should treat them.
- Rent-to-own and installment sale structures change the treatment entirely. If a home is sold to the tenant under a rent-to-own or installment contract, it may be treated as inventory rather than depreciable property, and it stops depreciating on the seller’s books.
- Tenant-owned homes on rented pads aren’t depreciable by the park owner. If the community owns the land but not the home, only the land and infrastructure depreciate. Getting this wrong is a frequent audit trigger.
This is exactly why a cost segregation study, rather than a generic depreciation schedule, matters for manufactured housing communities. The classification work has to match how the assets are actually owned and used, not just how they’re labeled on a closing statement.
The Take-Home
Manufactured homes depreciate in market value only when they’re treated like personal property on rented land. On your tax return, they depreciate in every case, but the schedule depends entirely on classification (real property, personal property, or land improvement).
If you’re acquiring a manufactured housing community, a proper re-classification of assets can mean hundreds of thousands of dollars in the first year of deductions under the current 100% bonus depreciation rules. Find a cost segregation provider who understands manufactured housing specifically, not just standard multifamily, is the difference between capturing that benefit and leaving it on the table.
About the Author
Ryan Nelson
I’m an investor, real estate developer, and property manager with hands-on experience in all types of real estate from single family homes up to hundreds of thousands of square feet of commercial real estate. RentalRealEstate is my mission to create the ultimate real estate investor platform for expert resources, reviews and tools. Learn more about my story.