
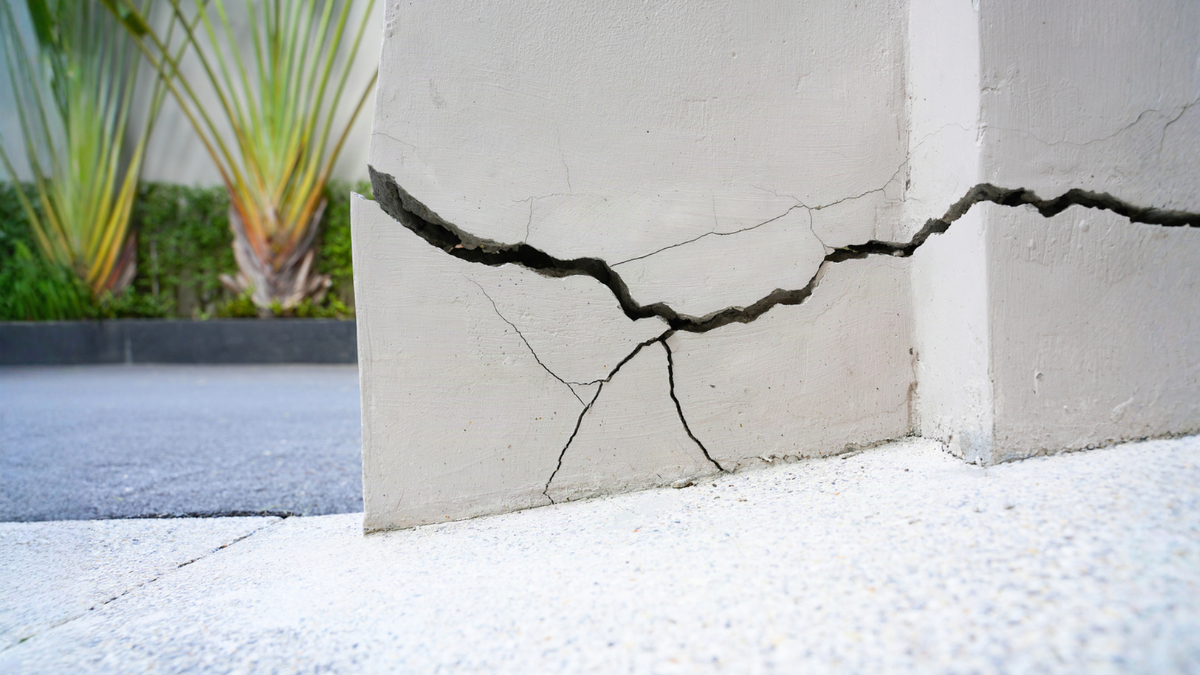
Purchasing a property is one of the most significant investments you’ll make in your lifetime, and ensuring its structural integrity is crucial. When considering home insurance for properties with subsidence, it’s essential to understand what challenges you may face. Subsidence is a real concern for many prospective homeowners, as it can significantly affect the value and safety of a property. This guide aims to explore key aspects to consider when buying a house with a history of subsidence.
Understanding Subsidence
Subsidence refers to the gradual sinking or caving in of land, which results in damage to the structures built upon it. This natural occurrence is most prevalent in areas with clay soil, as it tends to expand and contract with varying moisture levels. While not all properties are at risk, knowing the specific conditions that lead to subsidence can help you make more informed decisions.
Recognising the Signs
Before purchasing, it is important to identify any indications of subsidence. Common signs include cracks in walls or ceilings, doors and windows that refuse to shut properly, and rippling wallpaper where there’s no obvious damp. These symptoms alone do not confirm subsidence, but they do indicate that further investigation is warranted. A comprehensive survey by a qualified structural engineer can provide a detailed assessment of the severity of the issue.
Evaluating the Risks
If a property has a history of subsidence, you’ll need to evaluate the associated risks carefully. Subsidence can lead to costly repairs, not just to fix cosmetic damage, but also to stabilise the foundations of the building. Additionally, it might affect your ability to insure the property or could lead to higher premiums. Understanding these implications is vital to avoid potential financial pitfalls.
Mitigating the Problem
Fortunately, subsidence is not an insurmountable problem. Solutions such as underpinning, where a building’s foundations are strengthened, can effectively mitigate the issue. However, these solutions can be costly and time-consuming, so it’s important to factor them into your budget. Property sellers should be transparent about any previous problems and remedial work that has already been undertaken.
Securing Proper Insurance
Insuring a home with a history of subsidence can be complex, but it’s not impossible. While premiums may be higher, specialised insurance options are available to provide the necessary coverage. Ensure that you work with an insurance broker who understands the specifics of your situation, as they can tailor a policy that meets your needs while protecting against future subsidence events.
Conclusion
In conclusion, buying a home with a history of subsidence requires careful consideration and due diligence. Understanding the intricacies of such properties, recognising signs, assessing risks, and securing appropriate insurance are essential steps to ensure a sound investment. Though these challenges might seem daunting, they are manageable with the right information and professional guidance.
About the Author
Ryan Nelson
I’m an investor, real estate developer, and property manager with hands-on experience in all types of real estate from single family homes up to hundreds of thousands of square feet of commercial real estate. RentalRealEstate is my mission to create the ultimate real estate investor platform for expert resources, reviews and tools. Learn more about my story.